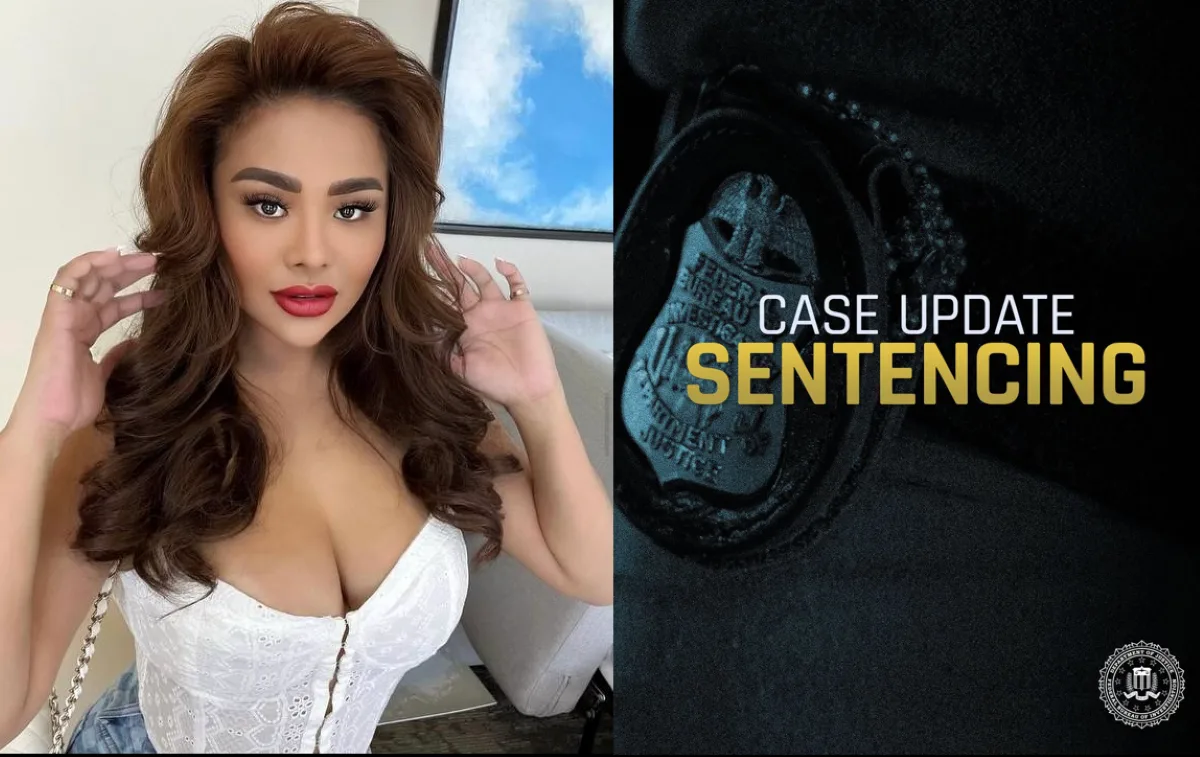
An Irvine woman was sentenced to 18 months in federal prison after admitting she failed to report more than $2.6 million in income tied to a sprawling cryptocurrency‑based criminal enterprise run by her former boyfriend, self‑styled crypto figure Adam Iza, known as “The Godfather.”

The sentence, issued by U.S. District Judge Percy Anderson, also requires $1,484,343 in restitution and the forfeiture of luxury vehicles, designer handbags, and multiple “Godfather” sculptures.
Case Overview
Federal prosecutors said Iris Rabaya Au, 37, helped Iza move, conceal, and spend millions in fraud proceeds between 2020 and 2024. Au pleaded guilty in March 2025 to subscribing to a false tax return, admitting she hid more than $2.6 million she transferred into her personal accounts.
According to court documents, Au created shell companies, opened bank accounts, and funneled illicit funds to pay approximately $1 million to corrupt Los Angeles County Sheriff’s Department deputies, purchase luxury real estate, cars, jewelry, and fund recreational spending valued at nearly $10 million. She also helped acquire $16 million in cryptocurrency for Iza.
Prosecutors said Au “set up the financial infrastructure” that allowed Iza to operate his schemes, conceal income, and personally benefit from the proceeds. She filed tax returns reporting only a fraction of her actual income, intentionally preventing the IRS from detecting the true amounts.
Iza, 26, previously pleaded guilty to conspiracy against rights, wire fraud, and tax evasion. He is already serving a 15‑year federal sentence for an attempted Bitcoin robbery and kidnapping in Connecticut. His sentencing in the California case is scheduled for October 5.
The investigation was led by IRS Criminal Investigation and the FBI.
National Trends in Tax Fraud and Crypto‑Related Financial Crimes
Federal data shows that tax fraud involving concealed income, shell companies, and digital assets continues to rise:
- IRS Criminal Investigation reports more than $37 billion in tax fraud identified nationwide since 2020, with cryptocurrency‑related tax evasion representing a rapidly growing share.
- FinCEN and the FBI note a year‑over‑year increase of 20–30% in crypto‑linked financial crimes, including unreported income, money laundering, and fraudulent transfers.
- The Department of Justice has charged more than 200 defendants in crypto‑related fraud cases since 2023, reflecting increased enforcement targeting digital‑asset abuse.
These cases often involve similar patterns: shell corporations, rapid movement of funds, luxury purchases, and attempts to obscure income from tax preparers and federal agencies.
How Organizations Can Prevent Fraud and Financial Abuse
Businesses, financial institutions, and digital‑asset platforms can reduce exposure to fraud schemes like the one described in this case by strengthening internal controls:
- Enhanced internal audits — Regular reviews of financial activity, vendor accounts, and unusual transactions.
- Stronger identity verification — Multi‑factor authentication and continuous monitoring for account takeovers.
- Robust access controls — Limiting who can open accounts, authorize transfers, or manage advertising and credit lines.
- Employee training — Teaching staff how to identify red flags in digital payments, crypto transactions, and shell‑company activity.
- Partnerships with law enforcement — Early reporting of suspicious activity to the IRS, FBI, or FinCEN.
Community Impact
This case highlights ongoing federal efforts to crack down on crypto fraud, tax evasion, and financial crimes involving digital assets, especially in Southern California.
With Orange County’s growing tech and finance sectors, federal agencies continue to warn businesses and individuals about the risks of unreported income, shell‑company misuse, and illicit cryptocurrency transfers.